Input 1 and Insillion Form Strategic Partnership to Expand Financial Infrastructure for U.S. Carriers and MGAs
Input 1 and Insillion partner to integrate policy administration, payments, and premium finance for U.S. carriers and MGAs.
MGA Policy Admin Suite 2.0 is built with an integrated partner ecosystem and new features designed to help your MGA grow faster. Read more.


Input 1 and Insillion partner to integrate policy administration, payments, and premium finance for U.S. carriers and MGAs.
MGAs have been at the forefront of specialty and excess and surplus lines growth with premiums growing by 14.5% to $89.9 billion in 2024. Their ability to underwrite hard-to-place risks and remain lean has made them a favorable distribution channel and investment for carriers and reinsurers alike.
How can AI-infused low code insurance platforms lead to faster development timelines for portals, testing and partner journeys
Explore the benefits of captive insurance, its business models, risk considerations, and key factors to consider before forming a captive.
See how Insillion Excel-to-API transforms Excel rating models into APIs, helping MGAs accelerate product launches.
Discover how GIG Takaful Kuwait modernized their core through Insillion and launched agent portals and distribution APIs in just six months.
Parametric insurance represents a modern and innovative approach to risk management. This unique structure is not only enhancing protection for established risks like natural catastrophes and weather events but is also enabling exciting new applications.
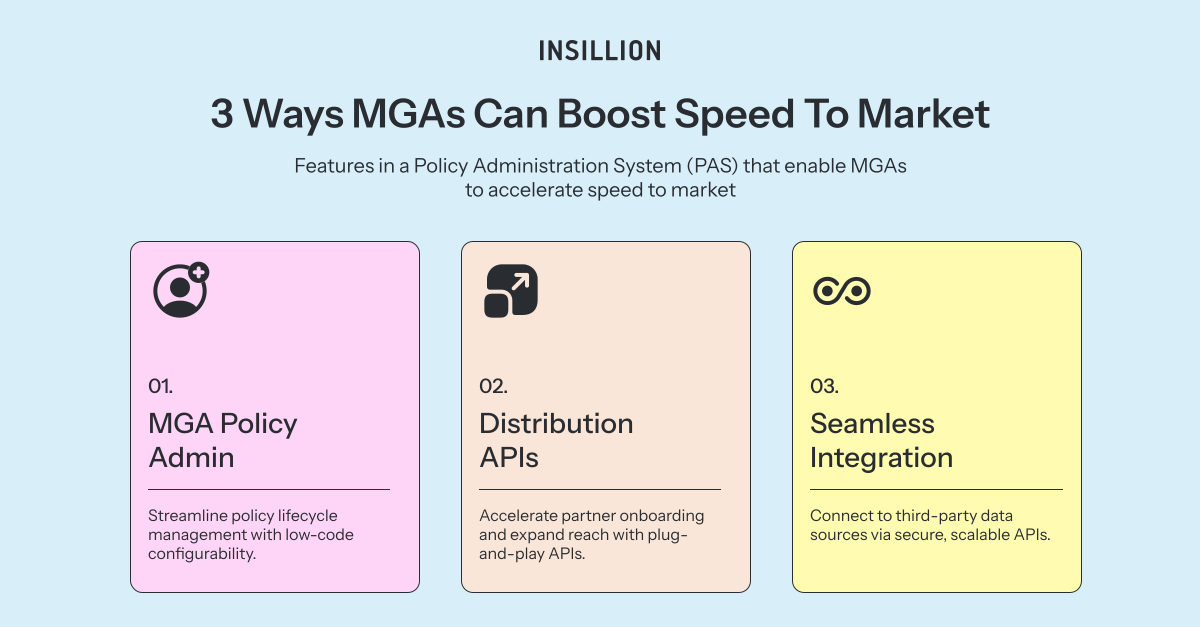
MGAs play a crucial role in the P&C insurance system, leveraging their deep industry knowledge and diverse distribution networks to offer specialized products.
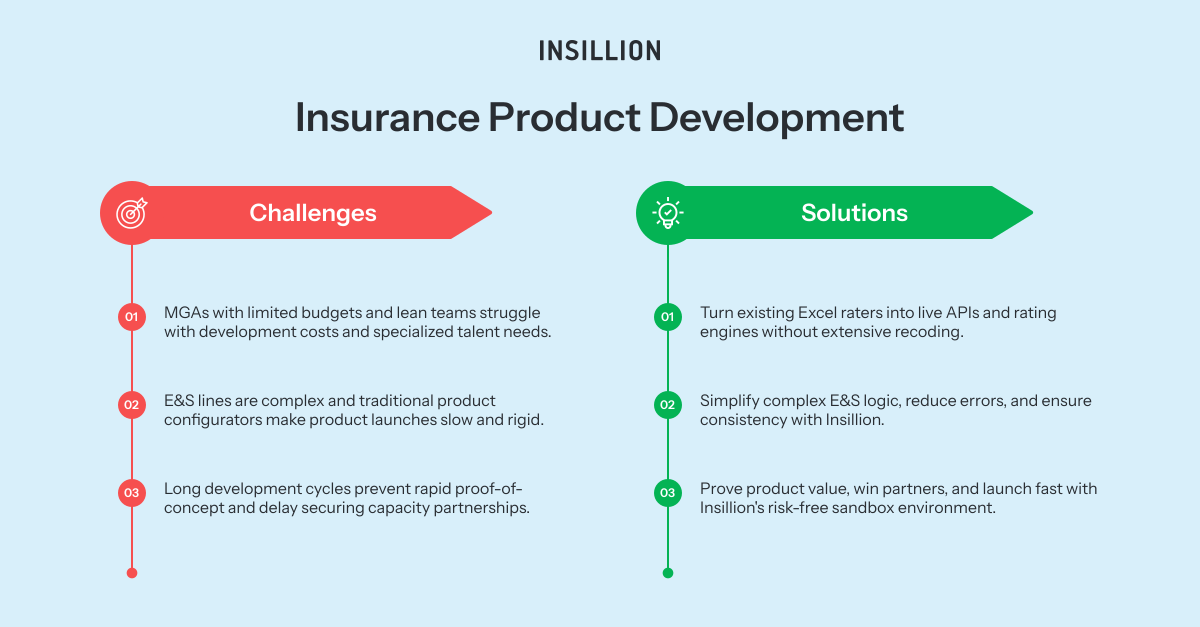
A new insurance product launch is especially challenging for startup MGAs. Most MGAs focus on niche or specialty lines (e.g. excess & surplus, cyber, and flood) that are complex to build
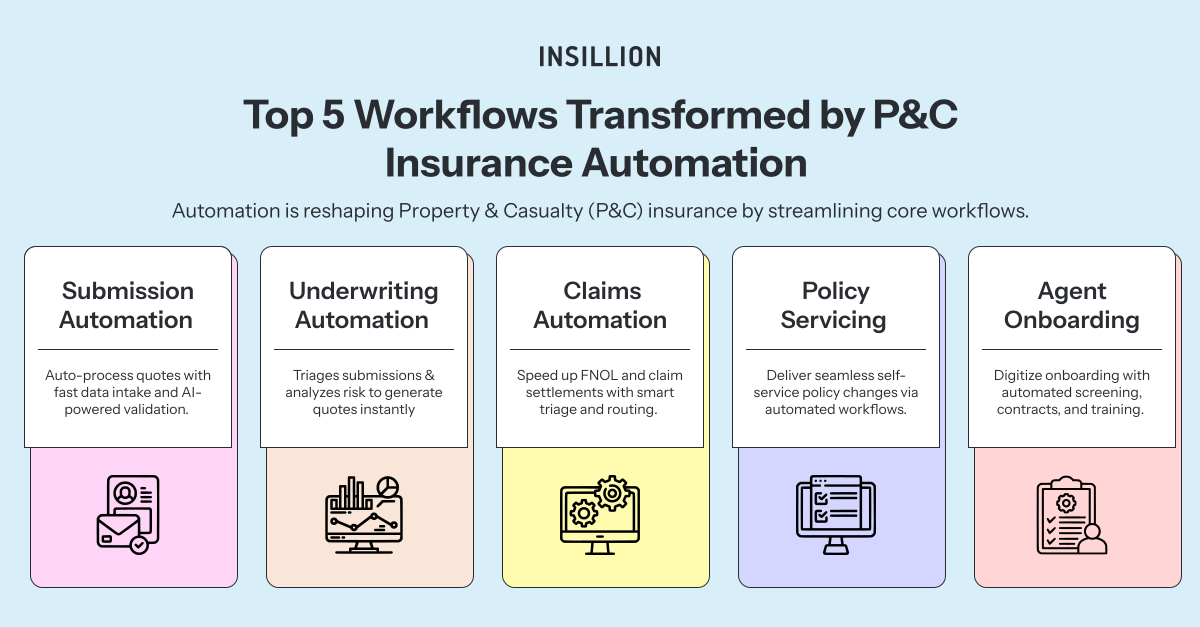
Commercial insurance underwriting is drowning in paperwork. Underwriters spend more time on manual tasks than on evaluating risks. The solution lies in automated underwriting systems that shift focus from administration to risk assessment.

Enabling faster product launches,
underwriting, and distribution
connectivity for insurance carriers and
MGAs worldwide.